Estate Planning Updates for 2026: Protecting Your Assets with a 50% Reduction in Probate Costs
As we approach 2026, the landscape of estate planning is set to undergo significant transformations, particularly concerning probate costs. For many, the very mention of probate evokes images of lengthy legal battles, complex paperwork, and substantial financial drains on an estate. However, the upcoming changes promise a beacon of hope: a potential 50% reduction in probate costs. This isn’t just a minor tweak; it’s a monumental shift that could fundamentally alter how individuals approach their legacies and asset protection. Understanding these 2026 estate planning updates is not merely beneficial; it’s essential for anyone looking to secure their financial future and ensure their loved ones are provided for without unnecessary burdens.
The implications of these changes are far-reaching, impacting not only the financial aspect of passing on assets but also the strategic decisions made during one’s lifetime. From updating wills and establishing trusts to reconsidering beneficiary designations, every facet of your estate plan will need a careful review. This comprehensive guide will delve into the specifics of these reforms, offering actionable insights and expert advice to help you navigate the new environment. Our goal is to empower you with the knowledge to leverage these changes, safeguard your assets, and ultimately, achieve peace of mind knowing your estate is prepared for 2026 and beyond.
Understanding the Core Changes in 2026 Estate Planning Legislation
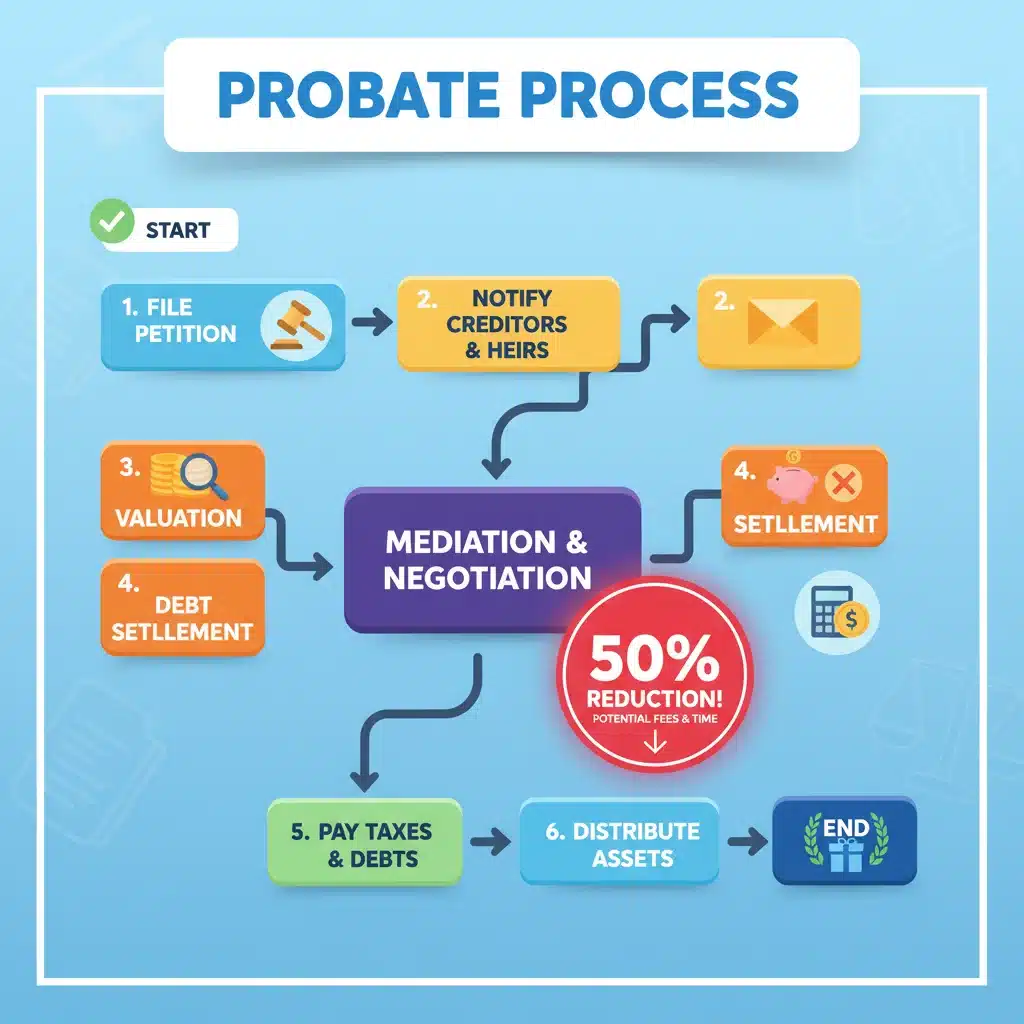
The anticipated 2026 estate planning legislation introduces several pivotal changes designed to streamline the probate process and significantly reduce associated costs. At the heart of these reforms is a concerted effort to minimize the administrative burden and legal fees that often plague estates, particularly smaller and medium-sized ones. Historically, probate has been a necessary but often cumbersome legal procedure that validates a will, inventories the deceased’s property, appraises the property, pays debts and taxes, and distributes the remaining property as the will (or state law, if there’s no will) directs. This process can be time-consuming, emotionally taxing for grieving families, and expensive, with costs often escalating due to legal fees, court costs, and executor commissions.
The primary driver behind the 50% reduction in probate costs stems from a combination of factors, including revised fee schedules, simplified procedural requirements for certain estate sizes, and increased encouragement for alternative dispute resolution methods. One of the most impactful changes is expected to be a restructuring of the statutory fees charged by executors and attorneys. Many states have traditionally had a percentage-based fee structure, meaning the larger the estate, the higher the probate costs. The 2026 estate planning updates are likely to introduce caps or a more progressive fee structure, potentially even fixed fees for estates below a certain threshold, thereby dramatically cutting expenses for many families.
Furthermore, there’s a strong push towards greater efficiency through technological advancements. Digital filing systems, online portals for document submission, and virtual hearings for non-contentious matters are all on the horizon, aiming to reduce the time and resources traditionally expended in the probate court system. These digital transformations are not just about convenience; they are about reducing the labor intensity of the process, which directly translates into lower costs for estates. The emphasis is on making the process more accessible and less intimidating for the average citizen, demystifying a legal procedure that has long been perceived as opaque and complex.
Another key aspect of the reforms involves a re-evaluation of the types of assets that are subject to probate. While some assets, like those held in revocable living trusts or with designated beneficiaries (e.g., life insurance, retirement accounts), typically bypass probate, the 2026 estate planning changes might expand the categories of assets that can be transferred outside of the traditional probate process. This could include higher limits for small estate affidavits or more straightforward transfer-on-death (TOD) and payable-on-death (POD) designations for a wider range of financial accounts and even real estate in some jurisdictions. Such expansions would allow more individuals to strategically plan their estates to avoid probate altogether, or at least a significant portion of it, thereby realizing substantial savings.
It’s crucial to recognize that while these changes aim for a universal reduction in costs, the specific implementation and exact percentage of savings may vary by jurisdiction. Estate laws are primarily state-specific, and while federal initiatives or model laws might influence state legislatures, each state will ultimately adopt and adapt these reforms in its own way. Therefore, staying informed about the particular legislative developments in your state will be paramount for effective 2026 estate planning. Consulting with an estate planning attorney who is well-versed in the upcoming state-specific changes will be indispensable to fully capitalize on these new opportunities.
Strategies to Maximize Your Savings: Leveraging the 50% Probate Cost Reduction
With the impending 50% reduction in probate costs, strategic estate planning becomes more critical than ever. This isn’t a passive benefit; it’s an opportunity that savvy individuals can actively leverage to maximize their estate’s value for their beneficiaries. The key lies in understanding which strategies align best with the new legislative framework and how to implement them effectively. The goal is not just to benefit from the automatic reduction but to proactively structure your assets and documents to minimize any remaining probate exposure and associated expenses.
Revisiting Your Will: A Cornerstone of 2026 Estate Planning
Even with reduced probate costs, a well-drafted will remains the cornerstone of any effective estate plan. The 2026 estate planning updates underscore the importance of ensuring your will is current, unambiguous, and compliant with the latest legal requirements. An outdated or poorly drafted will can still lead to complications, delays, and unnecessary legal challenges, even within a more streamlined probate system. Review your will to confirm that it accurately reflects your current wishes regarding asset distribution, guardianship for minor children, and executor appointments. Consider including provisions that specifically acknowledge the new probate procedures, if applicable, to further smooth the process.
Furthermore, if your will contains specific instructions that might now be redundant or less efficient due to the 2026 changes, it’s an opportune time to revise them. For instance, if you previously allocated specific assets to go through probate due to higher thresholds, those thresholds might have changed, making a different approach more beneficial. An experienced estate planning attorney can help you identify these nuances and update your will to be as efficient and cost-effective as possible under the new regulations.
The Power of Trusts: Bypassing Probate Entirely
While the 50% reduction in probate costs is significant, avoiding probate altogether remains the most effective way to eliminate these expenses entirely. This is where trusts, particularly revocable living trusts, shine in 2026 estate planning. When assets are properly transferred into a revocable living trust during your lifetime, they are typically not subject to the probate process upon your death. The trustee you designate can distribute the assets according to your instructions, privately and often much more quickly than probate.
The new legislation, by making probate less expensive, might inadvertently make some individuals question the necessity of a trust. However, the benefits of a trust extend beyond just cost savings. Trusts offer enhanced privacy, greater control over asset distribution (especially for beneficiaries with special needs or spending habits), and the ability to manage assets if you become incapacitated. For those with substantial assets or complex family situations, a trust remains an invaluable tool, providing a layer of protection and control that a will alone cannot. The 50% reduction makes probate less painful, but a trust makes it disappear for the assets held within it.
Optimizing Beneficiary Designations: A Simple Yet Potent Tool
Often overlooked, beneficiary designations on financial accounts, life insurance policies, and retirement plans are incredibly powerful tools for avoiding probate. Assets with properly named beneficiaries pass directly to those individuals upon your death, outside of the probate court’s jurisdiction. The 2026 estate planning updates highlight the importance of regularly reviewing and updating these designations. Marriage, divorce, births, deaths, and other life events necessitate changes to ensure your assets go to your intended recipients.
With the potential expansion of TOD (Transfer-on-Death) and POD (Payable-on-Death) options for a broader range of assets, this strategy becomes even more potent. Check with your financial institutions and legal counsel to see if new asset classes in your state can now utilize these direct transfer mechanisms. Leveraging these simple designations can significantly reduce the portion of your estate that might otherwise be subject to even the reduced probate costs, maximizing the inheritance for your loved ones.
Protecting Your Assets: Beyond Probate Cost Reduction in 2026
While the 50% reduction in probate costs is a welcome development, comprehensive 2026 estate planning extends far beyond merely minimizing probate expenses. True asset protection involves safeguarding your wealth from various threats, including creditors, lawsuits, long-term care costs, and even poor financial decisions by beneficiaries. The new legislative environment provides an excellent impetus to review your entire asset protection strategy.
Shielding Assets from Creditors and Lawsuits
Asset protection planning involves legally structuring your ownership of assets to make them less vulnerable to claims from creditors, lawsuits, or other legal judgments. While some strategies, like certain types of trusts (e.g., irrevocable trusts, domestic asset protection trusts), are designed explicitly for this purpose, even simpler measures can offer significant protection. For instance, holding assets jointly with rights of survivorship can offer some protection, as the assets may pass directly to the surviving owner, bypassing the deceased’s estate and potential creditors. However, the effectiveness of such strategies varies greatly by state law and the nature of the debt or claim.
The 2026 estate planning landscape encourages a deeper dive into how your assets are titled and structured. For business owners or professionals in high-liability fields, incorporating entities like LLCs or corporations can shield personal assets from business debts. Furthermore, ensuring adequate liability insurance coverage is a foundational, yet often overlooked, layer of asset protection. A thorough review with an attorney specializing in asset protection can identify vulnerabilities and recommend tailored solutions.
Addressing Long-Term Care Costs and Incapacity
One of the most significant threats to an estate’s value is the escalating cost of long-term care. Without proper planning, these expenses can quickly deplete a lifetime of savings, leaving little for heirs. The 2026 estate planning updates serve as a reminder to integrate long-term care planning into your overall strategy. This can involve purchasing long-term care insurance, exploring Medicaid planning strategies (if applicable and desired), or utilizing specific trust structures designed to protect assets while qualifying for government benefits.
Planning for incapacity is equally vital. A durable power of attorney for finances and an advance healthcare directive (or living will) are essential documents that ensure your financial and medical decisions can be made by trusted individuals if you become unable to do so. Without these, your family might have to go to court to establish a guardianship or conservatorship, a process that can be costly, public, and emotionally draining, regardless of the probate cost reductions.
Educating Your Beneficiaries
An often-underestimated aspect of asset protection is preparing your beneficiaries. While you might meticulously plan your estate to minimize taxes and probate costs, your efforts can be undermined if beneficiaries are unprepared to manage their inheritance responsibly. The 2026 estate planning environment offers an opportunity to engage in open conversations with your heirs about financial literacy, the responsibilities of inheriting wealth, and your intentions for the assets. For younger or less financially savvy beneficiaries, consider establishing trusts that distribute assets over time or provide for professional financial management. This ensures your legacy is preserved and used wisely, rather than being squandered or exposed to unnecessary risks.
The Role of Digital Assets in Your 2026 Estate Plan
In our increasingly digital world, neglecting digital assets in your 2026 estate planning would be a critical oversight. From social media accounts and email to cryptocurrency, online banking, and digital intellectual property, these assets have real value and significance. Without proper planning, they can become inaccessible or mismanaged after your death, causing distress for your loved ones and potentially leading to financial losses.
The 2026 estate planning framework, while primarily focused on traditional probate, implicitly encourages a comprehensive approach that includes digital assets. Many jurisdictions are now enacting or considering laws (like the Revised Uniform Fiduciary Access to Digital Assets Act, or RUFA) that grant fiduciaries (like executors or trustees) access to digital accounts. However, relying solely on these laws might not be sufficient. It’s far more effective to proactively include digital assets in your estate plan.
This involves creating a comprehensive inventory of all your digital accounts, including usernames, passwords (stored securely, ideally not directly in the will), and instructions for how you wish them to be handled. Do you want your social media accounts memorialized, deleted, or managed by someone? What about online financial accounts or digital currency? Specify your wishes clearly in a digital asset will or a separate memorandum referenced in your will. Appointing a digital executor or agent who understands your wishes and has the technical capability to manage these assets is also a wise step. This foresight can prevent significant headaches and ensure your digital legacy is managed according to your desires, even as probate costs are reduced for your physical assets.
Navigating Tax Implications with 2026 Estate Planning
While the focus of the 2026 estate planning updates is heavily on reducing probate costs, it’s imperative not to lose sight of the ever-present tax implications. Estate taxes, inheritance taxes, and capital gains taxes can significantly diminish the value of an estate if not properly addressed. The interplay between probate cost reduction and tax planning is crucial; saving on probate only to incur substantial taxes is a suboptimal outcome.
As of 2026, the federal estate tax exemption amount is subject to change. The Tax Cuts and Jobs Act of 2017 dramatically increased the federal estate tax exemption, but these provisions are set to sunset at the end of 2025. This means that, without new legislation, the exemption amount will revert to pre-2018 levels, adjusted for inflation, effectively halving the current exemption. This potential decrease in the federal estate tax exemption means that many more estates could become subject to federal estate taxes. Therefore, individuals with substantial wealth must re-evaluate their strategies to mitigate potential estate tax liabilities.
Strategies such as gifting during your lifetime (utilizing the annual gift tax exclusion), establishing irrevocable trusts, or charitable giving can help reduce the size of your taxable estate. For high-net-worth individuals, more sophisticated techniques like Grantor Retained Annuity Trusts (GRATs) or Irrevocable Life Insurance Trusts (ILITs) may become even more relevant. Furthermore, consider the state-specific estate or inheritance taxes, which can apply even if your estate falls below the federal exemption. Integrating these tax considerations with the new probate cost reductions is a complex task that requires the expertise of both an estate planning attorney and a tax advisor to ensure a truly optimized 2026 estate planning strategy.
Regular Review and Professional Guidance: Your Path to Successful 2026 Estate Planning
The dynamic nature of estate law, coupled with personal life changes, necessitates a commitment to regular review of your estate plan. The 2026 estate planning updates provide a clear and compelling reason to initiate this review now, but it shouldn’t be a one-time event. Life events such as marriage, divorce, birth of children or grandchildren, significant changes in assets or liabilities, changes in health, or even a change in your beneficiaries’ circumstances warrant a re-evaluation of your plan.
Attempting to navigate the complexities of estate planning, especially with significant legislative changes, without professional guidance can lead to costly mistakes and unintended consequences. An experienced estate planning attorney can provide invaluable assistance by:
- Interpreting New Legislation: Explaining how the 2026 estate planning updates specifically apply to your situation and jurisdiction.
- Tailoring Your Plan: Customizing strategies to meet your unique goals for asset protection, beneficiary provisions, and tax efficiency.
- Drafting Legal Documents: Ensuring your will, trusts, powers of attorney, and other documents are legally sound and compliant.
- Coordinating with Financial Advisors: Working in conjunction with your financial planner and tax advisor to create a holistic and integrated plan.
- Updating Your Plan: Advising on necessary adjustments as laws change or your personal circumstances evolve.
Beyond legal counsel, a holistic approach to 2026 estate planning also involves collaboration with other professionals. A financial advisor can help you understand the current value and growth potential of your assets, suggest appropriate investment strategies, and assist with beneficiary designations. A tax professional can offer insights into minimizing estate, inheritance, and income tax liabilities. This team-based approach ensures all aspects of your financial and legal life are considered, leading to a robust and resilient estate plan.
Conclusion: Embracing the Future of Estate Planning
The 2026 estate planning updates, particularly the projected 50% reduction in probate costs, represent a significant opportunity for individuals to refine and strengthen their legacies. This is a moment to move beyond reactive planning and embrace a proactive stance, ensuring your assets are protected, your wishes are honored, and your loved ones are spared unnecessary legal and financial burdens. While the cost reductions are a welcome relief, the true value lies in using this impetus to conduct a comprehensive review of your entire estate plan.
From meticulously updating your will and leveraging the power of trusts to optimizing beneficiary designations and addressing digital assets, every component of your estate plan deserves attention. Furthermore, integrating robust asset protection strategies and carefully navigating the evolving tax landscape are crucial for a truly secure future. The complexity of these changes underscores the indispensable role of professional guidance. Engaging with experienced estate planning attorneys, financial advisors, and tax professionals will not only help you understand the nuances of the new legislation but also empower you to craft a personalized, effective, and future-proof estate plan. By taking these steps now, you can confidently face 2026 and ensure your legacy is preserved exactly as you intend, with maximum efficiency and minimal cost.